- Digital Advertising
- Earnings Report
- Social Networks
Reddit Posts Record Profit as Google's AI Drains Its U.S. Audience
9 minute read
Revenue rose 53% to $895 million and margins widened, yet a warning that daily users could fall by a low double-digit percentage sent Reddit shares down about 18% after hours.
Key Takeaways
- Third-quarter revenue of $895 million beat the top of guidance by $25 million. Net income rose 74% to a record $283 million, and free cash flow nearly doubled to $363 million.
- U.S. daily users fell 2% to 50.7 million, the first decline since Reddit’s 2024 listing. Search referrals dropped by more than 1 million a week in October as Google leaned harder on AI answers.
- Reddit will test a logged-in-only experience outside the U.S. this quarter. It is accepting a smaller audience in exchange for deeper engagement, sharper ad signals and better-protected data.
A Quarter Built on Pricing Power
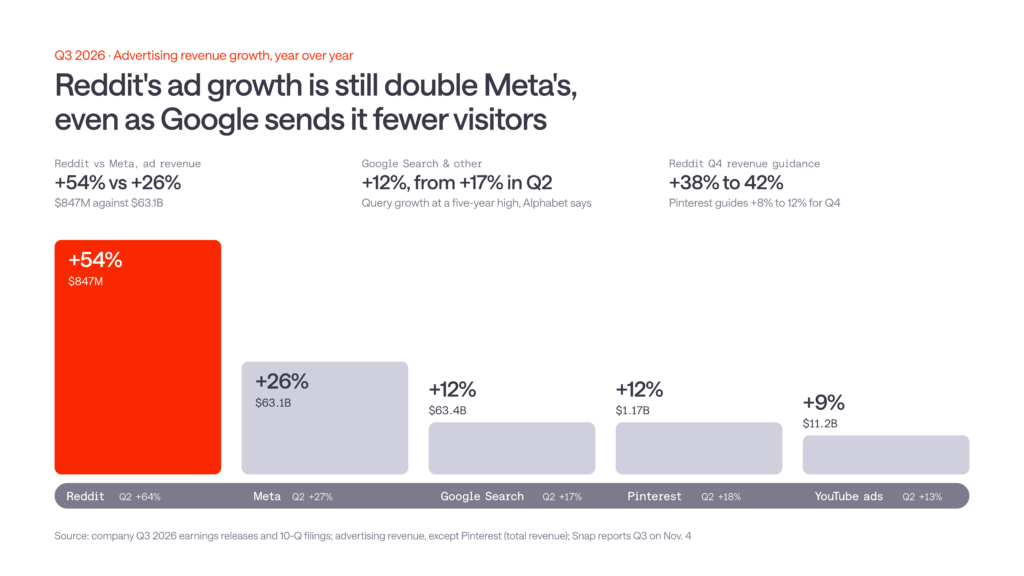
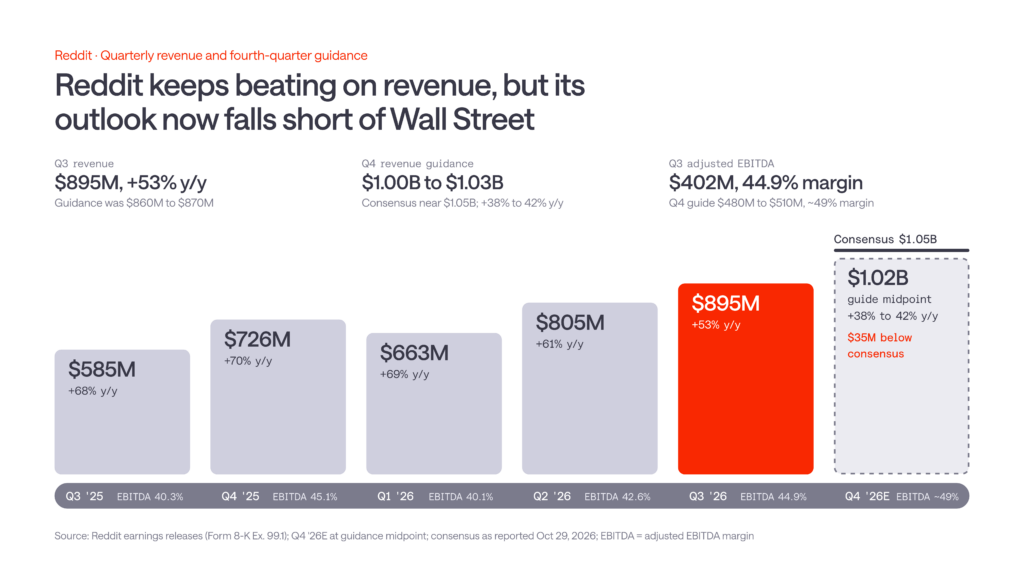
Reddit’s third-quarter results, released on October 29, had nearly everything investors ask of a growth company that has learned to make money. Revenue for the three months to September 30 rose 53% to $895 million. That was above the company’s own guidance of $860 million to $870 million and a consensus near $875 million. Advertising grew 54% to $847 million and still makes up almost all of the top line. Net income rose 74% to $283 million, the highest in the company’s history, or $1.40 per diluted share against $0.80 a year earlier. Adjusted EBITDA rose 70% to $402 million, a 44.9% margin. Capital spending was only $1 million, so operating cash flow of $364 million turned almost entirely into $363 million of free cash flow.
That balance sheet gives management unusual room to act. Reddit ended the quarter with $3.03 billion in cash, equivalents and marketable securities. It bought back about 670,000 Class A shares for $100 million at an average of $149.81, and fully diluted shares fell to 206.3 million. Trailing twelve-month revenue passed $3 billion. Yet the beat was smaller than the market has come to expect. In the second quarter, Reddit reported $805 million in revenue against guidance that topped out at $725 million. This time the margin was $25 million. Chief financial officer Drew Vollero told analysts that only about half of a quarter’s business is booked when it begins, and that some strong September demand could not be delivered. The explanation is plausible. It does little to restore confidence that the company will keep beating its own forecasts.
The Audience Google No Longer Sends
The problem is the number of people visiting, not the revenue. Daily active uniques rose 12% from a year earlier to 130.3 million. That missed the roughly 133.7 million analysts expected and was flat against the second quarter. In the U.S., which produced $719 million of the quarter’s revenue, daily users fell 2% to 50.7 million, down from 53.2 million in June. It was the first year-over-year decline since the company went public in 2024. The losses came mostly from logged-out visitors, the readers who arrive from a search result, get an answer and leave. Their U.S. count fell 4% to 27.3 million, while logged-in U.S. users grew just 1% to 23.4 million.
Management was unusually frank about the cause, and its warning for the coming quarter mattered more than the quarter just reported. Search referrals fell sharply during the period, the decline sped up in its final weeks, and in October referrals fell by more than 1 million a week on average. If that continues, Reddit said, total daily users could fall by a low double-digit percentage in the fourth quarter. That implies a base of roughly 113 million to 117 million, at or below the 116 million it reported a year ago. Chief executive Steve Huffman told CNBC that past Google algorithm changes tended to come and go. AI Overviews and AI Mode, he said, are “a fundamental shift in how the Google product works.” On the call, according to Reuters, he was blunter: AI Mode “does not drive traffic.”
Closing the Front Door
Reddit’s answer is to stop depending on visitors it has never managed to keep. This quarter it will start testing a mainly logged-in experience in select markets outside the U.S. If the change spreads, it would end two decades in which anyone could read the site without an account. The business case is clear. Logged-in and app users generate more than 80% of monetization, and both groups grew from the previous quarter in the U.S. and abroad. Requiring accounts improves personalization and ad targeting. It also makes Reddit’s archive harder to scrape, which Reddit is already fighting in court against Anthropic, Perplexity and three data-scraping firms.
The cost is just as clear, and management did not pretend otherwise. A smaller, more committed audience should lift revenue per user, which is already up 36% to $6.87 globally and 53% to $13.82 in the U.S. It also narrows the route by which casual readers have usually become members. Reddit has not said where login walls will go or whether a lighter logged-out version will survive, and analysts spent much of the call pressing on both points. Starting abroad, where revenue per user is $2.43, is a careful choice. It limits the revenue at risk while the company learns how retention and engagement respond.
Advertisers Are Still Buying
Nothing in the advertising data points to weaker demand. Chief operating officer Jen Wong said conversion volume more than tripled from a year earlier, clicks grew by more than half, and pricing rose faster than impressions. That means advertisers are paying more for each slot, not just buying more of them. Mid-market active advertisers rose by more than 50%. Shopping and app-install campaigns each grew by more than 95%, and international ad revenue rose 68%. Advertiser use of Reddit Max, the company’s automated campaign product, more than tripled from the prior quarter, and video ad revenue more than doubled. These gains come mostly from logged-in and app users, so management’s claim that it can earn more from a smaller audience has evidence behind it.
The data business gets less attention but may matter more strategically. Other revenue, which includes licensing, grew 35% to $48 million. That is a small figure next to the debate over what Reddit’s archive is worth to AI developers. Google and OpenAI are its main licensees. Huffman said talks with both are active but had nothing to announce. Any agreement must deliver fair value, he said, and Reddit might not sign a deal at all. The Wall Street Journal reported in July that Reddit had discussed restricting Google’s AI access under an arrangement reportedly worth about $60 million a year. A login wall strengthens Reddit’s hand in those talks, because content that cannot be freely crawled will increasingly have to be paid for.
What Investors Are Now Underwriting
The market reacted to the outlook, not the quarter. Reddit guided fourth-quarter revenue to $1.00 billion to $1.03 billion, growth of 38% to 42%, against consensus near $1.05 billion. It guided adjusted EBITDA to $480 million to $510 million, a margin near 49% at the midpoint. The shares had closed down 3.8% at $129.60 before the release. They then fell about 18% in extended trading to roughly $106.50. That is below their 52-week low of $119.27 and below any price since Reddit entered the S&P 500 on August 18. It was the second sharp post-earnings drop in three months. In July the stock fell nearly 21% intraday after second-quarter results, its steepest decline since the listing.
What has changed is the bet investors are being asked to make. For two years the case for Reddit rested on users and revenue per user rising together. The third quarter delivered rising revenue per user while user growth stalled in the company’s most valuable market. Vollero has named $5 billion in annual revenue as the next internal target. With $3 billion in cash and margins near 45%, Reddit can afford to pursue it through a transition that, by its own forecast, will shrink reported users before any benefit shows. Its growth still outpaces Snap and Pinterest. Investors may come to see Reddit as a smaller, more valuable network, or keep discounting it as a site that depends on Google’s search results. The answer will come from the first results of the international login tests, and from whether advertisers follow the users who stay.