- AI
- Digital Revenue
- Earnings Report
- Streaming
Spotify’s Pricing Power Buys Patience for Its Costly AI Build-Out
9 minute read
Spotify met every third-quarter target and guided fourth-quarter profit above consensus, showing investors that higher prices can finance a heavier AI and marketing budget.
Key Takeaways
- Revenue rose 16% to €4.97 billion, or 14% at constant currency, as Premium subscribers reached 306 million and price increases supplied roughly half of Premium’s underlying growth.
- Operating expenses climbed 26% on marketing, cloud and AI spending, holding operating margin at 13.5%, while lower finance income and a tax swing cut diluted EPS to €2.48.
- Shares rose 3% to 5% premarket as fourth-quarter operating income guidance of €820 million topped the €813.4 million LSEG consensus, implying a margin near 15.8% by year-end.
The Value of Saying What You Will Do
Spotify’s third quarter mattered less for any surprise than for how closely it matched what management had promised. For the three months to September 30, the Luxembourg-domiciled company reported revenue of €4.97 billion, up 16% from a year earlier and 14% at constant currency. Favorable exchange rates added roughly 190 basis points. Monthly active users reached 788 million, exactly on guidance, and Premium subscribers rose to 306 million, one million ahead of plan. Gross margin of 33.0% was the highest Spotify has recorded in any third quarter. Operating income of €672 million cleared the company’s own forecast by €2 million. None of these numbers was spectacular. Taken together, they were exact, and exactness was what the moment required.
The reason lies in the year Spotify has had. This is the first year under co-chief executives Alex Norström and Gustav Söderström, who succeeded founder Daniel Ek in January when he became executive chairman. In August, their second-quarter outlook combined a softer user forecast with a sharp increase in marketing and AI spending. The softer forecast reflected a deliberate choice to add friction to the free tier in select emerging markets to push conversion. Investors read that ambition as drift, and the shares fell. On October 21 the stock closed at $525.34, well below the roughly $644 at which it traded on the eve of last year’s third-quarter report. Norström’s summary of the quarter was pointedly plain: “This was a quarter where we did what we said.” For a new leadership team asking for patience, that sentence carried more weight than any single metric.
Price Becomes the Growth Engine
Beneath the headline, the more consequential change is in how Spotify grows. Premium revenue rose 17% to €4.49 billion, or 15% at constant currency, on 9% subscriber growth and average revenue per user of €4.95, up 9.3%. Excluding currency, ARPU advanced 7.5%, a gain the company attributes to price increases partly offset by product and market mix. Put simply, about half of Premium’s underlying growth now comes from charging existing customers more. That is the signature of a mature subscription franchise, and the striking detail is that subscriber growth has not suffered for it. Six million net additions came from every region, helped by promotional campaigns and partnerships. Premium gross margin widened 130 basis points to 34.5% as revenue outran music, audiobook and video podcast costs. Raising prices while the base keeps growing is the clearest evidence of pricing power a subscription business can offer.
Advertising, long the weak spot in the model, finally showed signs of life. Ad-supported revenue grew 10% to €482 million, or 9% at constant currency, a marked improvement on 1% reported growth in the second quarter. Automated sales channels remained the main contributors. Music advertising expanded on higher impressions even as pricing stayed soft, and sponsorship gains in Spotify’s owned and licensed podcasts added momentum. Segment gross margin rose 105 basis points to 18.7%. Even so, the business generates less than a tenth of group revenue from 499 million ad-supported users, which makes it the largest underused asset on the platform. One quarter of acceleration does not settle that question, though it suggests the machinery is beginning to turn. Segment comparisons reflect a January reclassification that moved some revenue from advertising into Premium.
The Cost of Building Ahead
The bill for Spotify’s ambitions shows up in operating expenses, which rose 26% to €967 million. Excluding currency and social charges, the payroll taxes that move with the company’s share price, the increase was 19%, driven by marketing alongside cloud and AI compute. Research and development alone climbed 35%. Social charges swung from a €16 million credit a year earlier to a €22 million cost, €13 million above forecast because the stock rose during the quarter. Full-time headcount slipped to 7,284 from 7,302 in June, so the money is going into servers and customer acquisition rather than hiring. The operating margin of 13.5%, essentially unchanged from a year ago, sums up the trade. Spotify is earning more on every euro of revenue at the gross level and choosing, for now, to spend the difference.
That choice produced the quarter’s most misread figure. Diluted earnings per share were €2.48, against €3.28 a year earlier and an LSEG consensus near €2.80, and early headlines called it a miss. The shortfall comes from below the operating line. Net finance income fell to €33 million from €245 million, and income tax swung from a €72 million benefit to a €187 million charge. Net income fell to €518 million from €899 million even as operating income rose 15%. The cash picture is steadier than the earnings line suggests. Free cash flow of €735 million fell 9% on working capital movements, but trailing twelve-month free cash flow stands at €3.2 billion and liquidity at €9.9 billion. The exchangeable notes outstanding at the start of the year have already been repaid. This balance sheet can absorb an investment year without strain.
From Catalog to Agent
The product agenda shows where the spending lands, and it follows a coherent economic logic. Spotify announced that audiobooks will expand from 22 markets to more than 180 by the end of 2026, with more than 350,000 titles across over 120 languages. It launched Creator Memberships in 34 markets, letting podcasters sell paid tiers directly to their audiences. It also extended its Partner Program to more than 35 new markets, including Italy, Spain, Brazil and Mexico. The common thread is margin. Each initiative steers listening toward formats whose costs sit outside the recorded-music royalty structure that has long capped Spotify’s profitability. The company credits exactly that mix for its Premium margin gains. Broadening the catalog is a quiet way of loosening the labels’ grip on its economics.
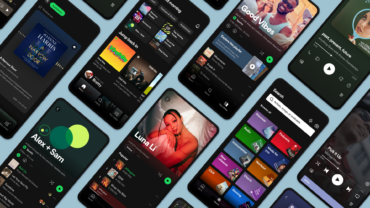
Artificial intelligence runs through the rest of the roadmap. A new integration with Muse lets listeners control Spotify through a conversation with an AI agent, from playback to playlist building. Taste Profile gives U.S. Premium users an editable view of how the service models their preferences. Managed Accounts for children 13 and under now reach families in six markets. These follow second-quarter launches of AI-generated Personal Podcasts, DJ in four new languages, and Reserved, an early-access ticketing feature built with Live Nation. Söderström contends that Spotify is positioned to “thrive in the agentic age.” The argument rests on a question that will shape the next phase of consumer software: whether Spotify becomes the destination agents send listeners to, or the interface they quietly replace. Investors are also weighing AI music generators such as Suno and Udio, so the compute bill is as much defense as offense.
What the Market Bought, and What Comes Next
Investors weighed the EPS line against the outlook and sided with the outlook. Spotify guided fourth-quarter operating income to €820 million, above the €813.4 million LSEG consensus. It forecast 316 million Premium subscribers against a Visible Alpha estimate of 314.7 million. Its forecast of 818 million monthly active users sat a fraction below the 819 million expected, a gap investors chose to overlook. Shares rose between 3% and 5% in volatile premarket trading, within the roughly 9% move options had priced. The response reverses August, when a cautious outlook overshadowed a record margin. It also follows the board’s August 20 decision to add $1.5 billion to its repurchase authorization, bringing the total to about $2.2 billion. Spotify has bought back $1.1 billion of stock this year through October 21, a clear statement of how management views its own valuation.
The fourth quarter now tests management’s central claim that the spending surge is temporary. Revenue guidance of €5.2 billion includes a currency tailwind of about 230 basis points. That implies constant-currency growth of roughly 12% to 13%, a modest slowdown from the third quarter. The €820 million operating target implies a margin near 15.8%, more than two points above the latest quarter. It would lift full-year operating income to about €2.86 billion, roughly 30% above 2025. Gross margin guidance of 33.8% leaves little room for error, and social charges add swings of about €20 million for every 10% move in the share price. If Spotify delivers, 2026 will look less like a year in which margins were sacrificed than one in which they were deferred. If it falls short, the market’s newly restored patience is unlikely to stretch as far a second time.